
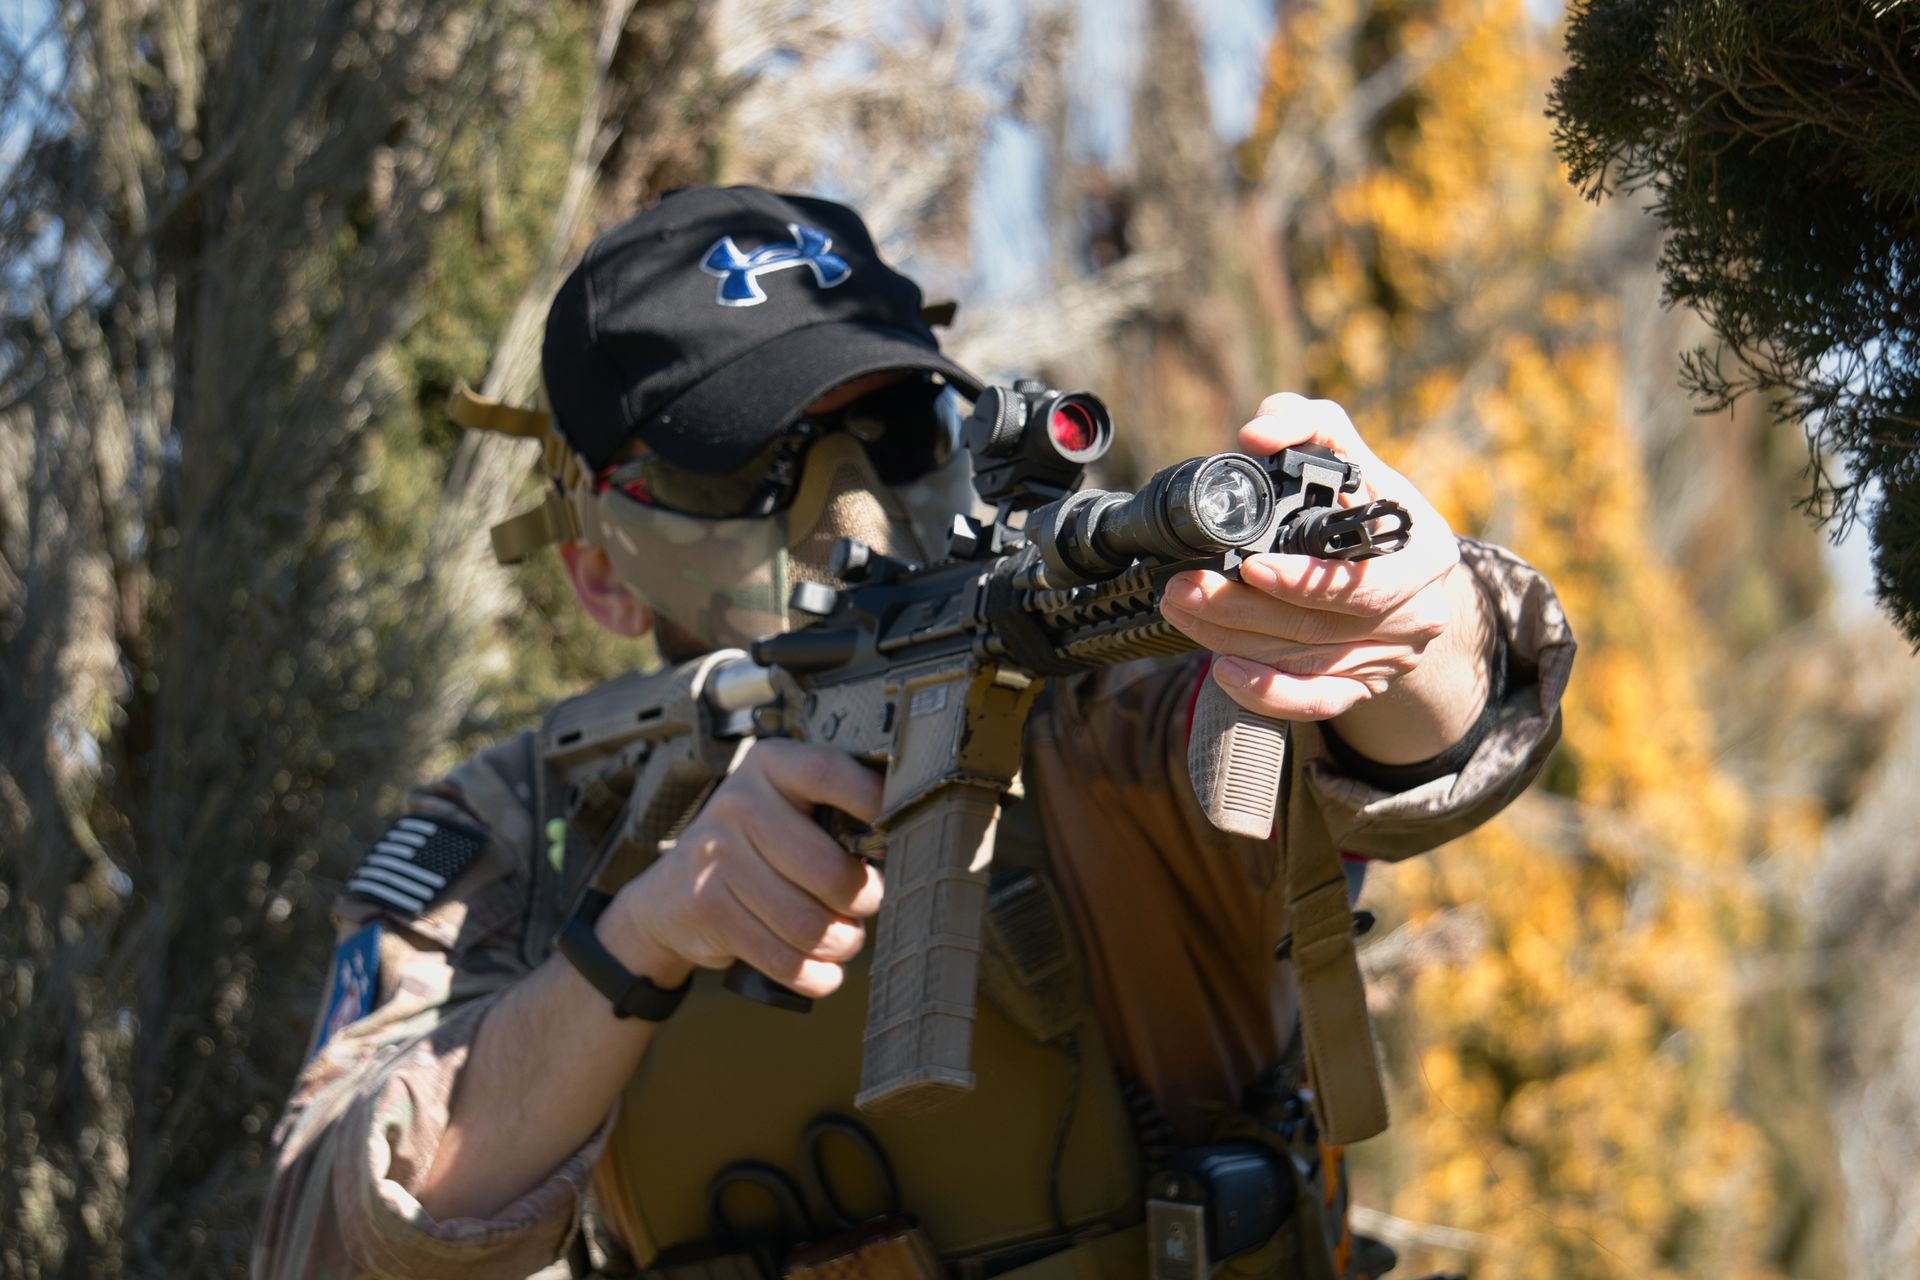
Search "airsoft field insurance" and the first quote you see is a bare General Liability policy at minimum limits. That quote is real, and for a commercial field it is close to useless. The standard General Liability form excludes injury to sports and athletic participants, so it almost never covers the one thing an airsoft field reliably produces a claim for: a paying player hit in the eye. A real program prices each line on its own, starting with General Liability at $500 to $1,500 a year and Participant Injury at $250 to $750, and the step from that cheap quote to a policy that actually pays a player's eye claim is the entire subject of this guide.
Here is what airsoft field insurance really costs in 2026-2027, the seven drivers that move your rate up or down, and how to get a number that fits your operation instead of a generic one off a search result.
What airsoft field insurance costs in 2026-2027
For a new commercial airsoft field General Liability runs roughly $500 to $1,500 a year at $1,000,000 per occurrence and $2,000,000 aggregate limits, and Participant Injury, the cover for the players themselves, runs $250 to $750. Commercial Property on the rental fleet runs $500 to $2,000 a year, and Workers' Compensation once you have staff runs $200 to $1,000, rated against your equipment schedule and your payroll. If you are still deciding what that program has to include, start with does an airsoft field need insurance.
2026-2027 premium benchmark
What airsoft field insurance costs, line by line
Typical annual premiums for a US commercial airsoft or milsim field.
- Priced for
- Commercial airsoft or milsim field, outdoor, indoor or close quarters battle
- Basis
- Annual premium, United States
- Updated
- September 2026
| Coverage | Typical annual range | Monthly estimate | Typical limits |
|---|---|---|---|
| General Liability InsuranceFoundation Third-party bodily injury, property damage and legal defense, including a spectator hit by a stray BB or a parent who slips in the lobby. | $500 to $1,500 | $45 to $125per month | $1,000,000 per occurrence / $2,000,000 aggregate |
| Participant Injury InsuranceFoundation Liability for injuries to the paying player, a BB to the eye or a twisted ankle in close quarters, which a standard liability form excludes. | $250 to $750 | $25 to $65per month | $1,000,000 per occurrence |
| Commercial Property InsuranceFoundation The rental fleet of automatic electric guns, chronographs, netting, barricades and pro-shop stock, scheduled at replacement cost. | $500 to $2,000 | $45 to $170per month | Based on total insurable value |
| Workers' Compensation InsuranceFoundation Referees, chronograph staff and party hosts injured at work. Required in most states once you have employees, with thresholds that vary. | $200 to $1,000 | $20 to $85per month | Statutory state limits |
Participant Accident Insurance, the no-fault medical cover for players, is priced on top of these lines. Inland Marine Insurance, Liquor Liability Insurance and Excess / Umbrella Insurance are not part of the standard airsoft program, though mobile and pop-up operations also need Inland Marine Insurance and Commercial Auto Insurance for hired and non-owned vehicles. Product Liability Insurance for a pro shop selling guns, BBs and gas, and Event Insurance for off-site milsim games, are quoted separately where the operation needs them.
Premium ranges per the Specialty Insurance book. Updated . Ranges are an indication for budgeting, not a quote or a bindable offer.
Get a 24-hour quoteThe table prices each line on its own, so it is not a program total, and it is not a quote.
Where your field lands inside each range depends on the shape of your operation:
- By-appointment-only or small private fields sit below the range.
- New outdoor commercial fields sit in the middle of it.
- Indoor and close-quarters-battle arenas sit higher, on higher slip-and-fall density, fire load, and lighting risk (we compare the two venues in indoor vs outdoor airsoft fields).
- Mobile and multi-site operations sit highest, because they trigger auto, inland marine, and per-venue certificates.
Airsoft prices below a comparable paintball field on the core lines: General Liability runs $500 to $1,500 a year against $700 to $2,500 for paintball, and Participant Injury $250 to $750 against $250 to $1,000. Eye and dental injury exposure is what a carrier weighs on the class. We break that comparison down in our airsoft versus paintball insurance guide. The seven drivers in the next two sections are what decide where in each range your field lands, and most of them are inside your control.
Why a real airsoft policy costs more than the online number
The few-hundred-dollar quote is cheap for a reason, and the reason is the form, not the carrier being generous. A policy that cheap is almost always a bare Commercial General Liability form, and the standard General Liability form excludes injury to anyone "practicing for or participating in any sports or athletic contest or exhibition." On an airsoft field, every player is a participant. So the bargain quote covers the spectator who slips in your lobby and excludes the player who took a BB to the eye, which is the claim an airsoft field is most likely to see.
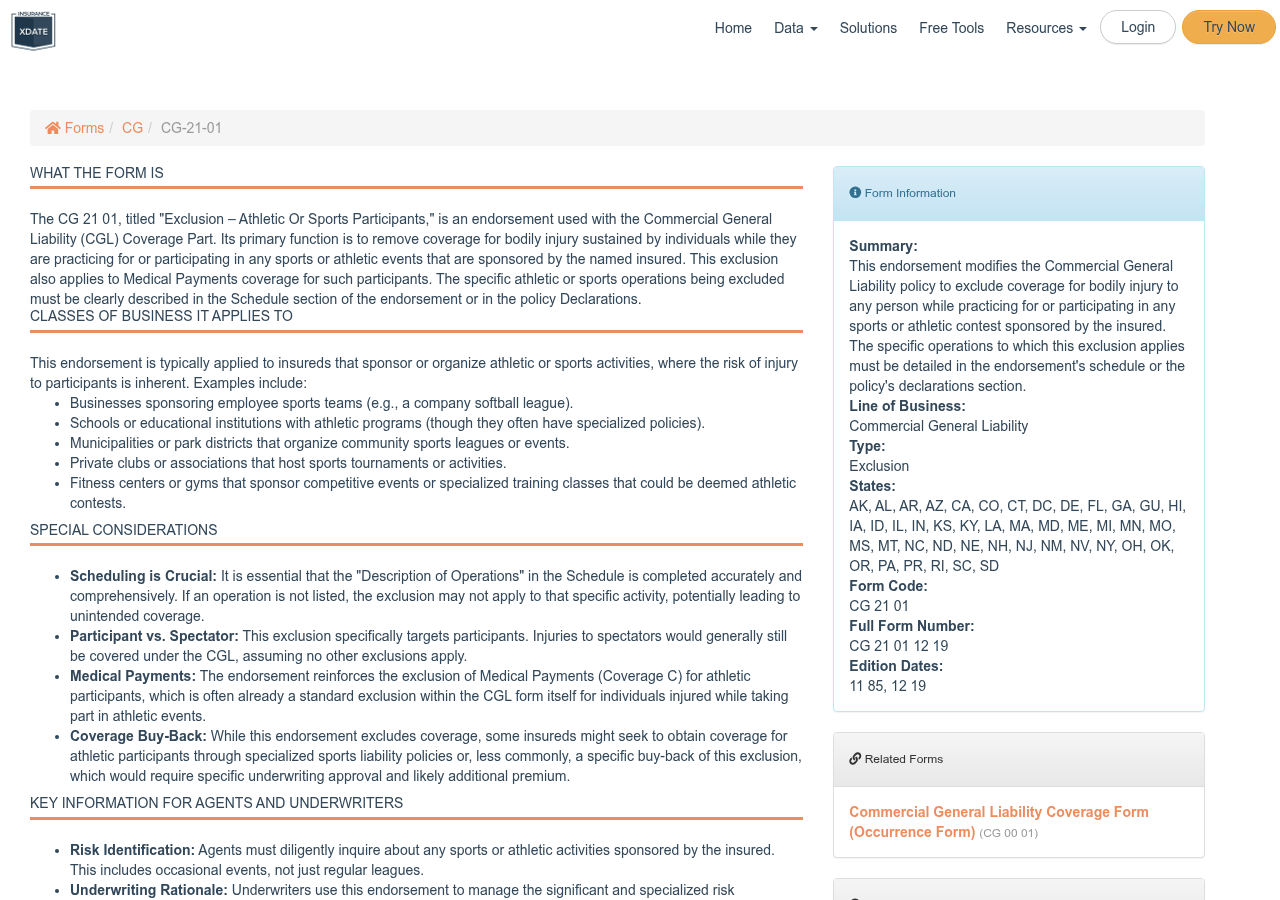
Source 1 of 2 · Standard ISO exclusion form
The standard ISO CG 21 01 endorsement removes coverage for athletic and sports participants. On an airsoft field that is every player, which is why a cheap General Liability-only quote is cheap: it leaves out the coverage your players most need.
A real airsoft program prices four coverages, not one. The table below is what your premium is buying, and what the discount quote leaves on the table.
| Coverage | What it pays for | In the cheap quote? |
|---|---|---|
| General Liability | The spectator hit by a stray BB, the parent who slips in your lobby, damage to a rented building | Usually yes, at minimum limits |
| Participant Injury | The paying player hurt during a game, the coverage the standard General Liability form excludes | Almost never |
| Property | Your fleet of automatic electric guns, chronograph, netting, barricades, and pro-shop stock | Rarely, and rarely at replacement cost |
| Workers' Compensation | Referees, chronograph staff, and party hosts injured at work, required in most states once you hire | No, it is a separate policy |
When a field shows me a few-hundred-dollar quote, the number is not the problem. The form is. A policy that cheap is almost always a bare General Liability form with the participant excluded, which means the one injury an airsoft field reliably produces, a BB to a player's eye, is the one it does not cover. You are not buying cheap insurance. You are buying no insurance for the player, with a receipt.
Bobby Sharp, Action Sports Practice Lead, Specialty Insurance
For a fuller picture of where a generalist policy quietly leaves an action-sports operation exposed, our breakdown of the coverage gaps a generalist agent will miss covers the same ground from the buyer's side.
What pushes an airsoft field's premium up
Seven drivers move the number the most. The first three carry the most weight with an underwriter.
| Driver | Why underwriters charge more for it |
|---|---|
| Indoor or CQB operation | Higher slip-and-fall density, fire load, and lighting risk than an open outdoor field |
| Mobile or pop-up component | Triggers Hired-and-Non-Owned Auto, Inland Marine on the fleet in transit, and per-venue certificates |
| Loss history | A prior eye or dental claim is the single biggest rate-up an airsoft field carries |
| Mesh lower-face protection allowed | Raises dental injury frequency, a known cost driver for the class |
| High muzzle velocity without minimum engagement distances | Higher impact energy, higher injury severity, higher claim cost |
| Alcohol service on-site | Adds liquor liability and dram-shop exposure on top of the field risk |
| Open public play versus private bookings | More players, more turnover, more claim frequency |
The injury profile is the reason airsoft is priced as a hard class in the first place. The American Academy of Ophthalmology reports that eye injuries from non-powder guns, the category that includes airsoft, BB, and pellet guns, have risen sharply, with air-gun-related hospital admissions up roughly 600 percent since 2010 and the average age of the injured patient dropping from 16 to 9. A meaningful share of those young patients still had reduced vision after treatment. That severity is exactly what an underwriter prices against.
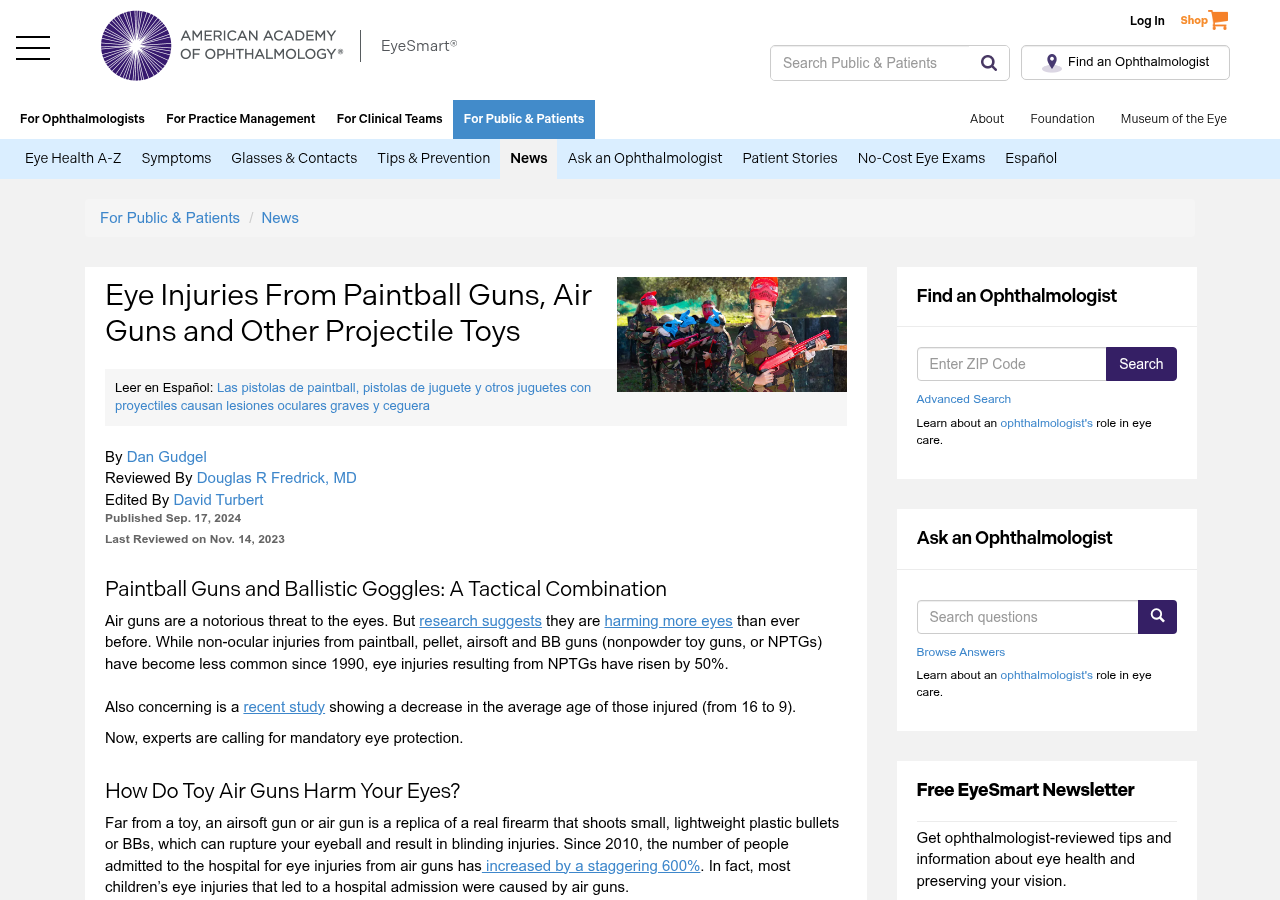
Source 2 of 2 · Clinical injury record
The American Academy of Ophthalmology documents the rise and severity of air-gun and airsoft eye injuries. That severity profile is what carriers underwrite against, and the reason airsoft carries a surcharge over a comparable lower-impact class.
Source: aao.org/eye-health/news/combating-eye-injuries-from-air-guns
What brings an airsoft field's premium down
The good news for operators: most of the levers that lower your rate are documentation habits, not capital spending. An underwriter prices what you can prove.
| Tactic | What it does to your premium |
|---|---|
| Mandatory sealed, impact-rated eye protection for everyone on the field | Removes the most expensive and most frequent claim driver the class has |
| Enforced muzzle-velocity cap, chronographed at check-in, with minimum engagement distances | Lowers injury severity, the lever underwriters weigh most after loss history |
| A chronograph log and signed safety briefings kept on file | Turns your safety claims into evidence an underwriter can price on |
| Clean three-year loss history | The biggest premium mover there is, once you are in the specialty market |
| Property scheduled at replacement cost | Stops an undervalued fleet from leaving you underinsured, and keeps the property line priced accurately |
| Annual waiver on file for every participant | Cleaner claim defense, which the carrier sees in your loss runs over time |
The single biggest lever on an airsoft premium is not the carrier. It is the file you hand me at renewal. A documented velocity cap, a chronograph log, sealed eye protection enforced for everyone on the field: a field that can produce those prices below one that only promises them. Underwriters price what you can prove, not what you say.
Bobby Sharp, Action Sports Practice Lead, Specialty Insurance
The other reason your rate may look high is classification. Airsoft is usually placed through the specialty and excess-and-surplus market, the part of the industry built to price risks the standard admitted market will not write. A generalist who has to shop your field one carrier at a time will quote slower and higher than a broker who writes the class on purpose. The same under-scheduling that inflates a property line shows up across action-sports policies, which we cover in why your field's General Liability policy probably has gaps.
Where your operation lands on premium
The line ranges above are the starting point. The chart below maps roughly where each operation type sits relative to a new outdoor field, the same picture an underwriter builds before quoting.
Two fields with the same revenue can be thousands of dollars apart at renewal because of safety controls and loss history alone. That is why a real quote starts with your operation, not a price list.
How to get an accurate airsoft insurance quote in 24 hours
Most generalist agents take days to quote airsoft, if they will quote it at all, because they have no specialty form on hand and are shopping the open market one carrier at a time. A broker who writes the class turns it around in 24 to 48 hours. To get there fast, your underwriter needs five things:
- A completed application with your site, play format, and rental fleet count
- Your prior declarations page, or a note that you have never been insured
- Loss runs from any prior carrier
- Your current waiver template
- Your chronograph log and velocity cap policy, if you are already operating
If you have those five, a specialty broker can usually quote in two business days and bind shortly after. If you do not have all five, a good broker tells you what they can quote now and what to assemble for the best renewal pricing later. That risk-band thinking is what operators hear back from us in the first day after they send a declarations page, and it is why the reviews read the way they do.
"Specialty Insurance is a great choice! I highly recommend this company for your business! They diligently take their time and work with you, making sure your business has all the correct and specific coverages you need. Cathy was a huge help, and gave me exactly what I needed, making it budget friendly and greatly affordable. Choose Specialty Insurance if you want the best service and fair treatment for your business!"
Talk to an airsoft specialty broker before you compare quotes
The cheapest line on a quote is rarely the cheapest policy once a claim lands. Before you choose on price, get a quote from a broker who writes airsoft field insurance on purpose, builds Participant Injury into the program rather than leaving it out, and schedules your Property on what your field truly owns. Then compare like for like. A real number for your operation beats a generic one every time.
Frequently Asked Questions
How much does airsoft field insurance cost per year?
For a new commercial airsoft field, General Liability runs roughly $500 to $1,500 a year at $1,000,000 per occurrence and $2,000,000 aggregate limits, and Participant Injury for the players runs $250 to $750. Commercial Property runs $500 to $2,000 and Workers' Compensation $200 to $1,000. Each line is priced on its own. Indoor, CQB, and mobile operations sit higher, and by-appointment or small private fields sit lower. Your safety controls and loss history move the number more than anything else.
Why is the airsoft insurance I found online so cheap?
Because it is usually a bare General Liability policy at minimum limits, and the standard General Liability form excludes injury to sports and athletic participants. On an airsoft field every player is a participant, so the cheap quote covers your spectators and excludes your players, the people most likely to be hurt. A real program adds Participant Injury, Property, and Workers' Compensation, which is why it costs more.
Is airsoft insurance more expensive than paintball insurance?
Usually not. Airsoft prices below a comparable paintball field on the core lines: General Liability runs $500 to $1,500 a year against $700 to $2,500 for paintball, and Participant Injury $250 to $750 against $250 to $1,000. Eye and dental injury exposure is what a carrier weighs, especially where mesh lower-face protection is allowed. When participant volumes and safety controls are similar, the two land close together. See our airsoft versus paintball insurance guide for the comparison.
What raises an airsoft field's insurance premium the most?
After loss history, the biggest drivers are an indoor or CQB operation, a mobile or pop-up component, allowing mesh lower-face protection, and high muzzle velocity without minimum engagement distances. Alcohol service and high open-play volume add to it. Most of these are within your control through your safety rules.
How can I lower my airsoft field's insurance cost?
Enforce sealed, impact-rated eye protection for everyone on the field, run a chronographed velocity cap with minimum engagement distances, and keep a chronograph log and signed safety briefings on file. Schedule your property at replacement cost and keep a clean loss history. An underwriter prices what you can document, so the field that hands over a clean file at renewal earns the best pricing the specialty market offers.
Sources
- ISO Commercial General Liability form CG 21 01, Exclusion of Athletic or Sports Participants (insurancexdate.com): the standard endorsement that removes coverage for sports and athletic participants, the coverage a cheap General Liability-only airsoft quote leaves out.
- American Academy of Ophthalmology, "Eye Injuries From Paintball Guns, Air Guns and Other Projectile Toys" (aao.org): clinical record of the rise and severity of air-gun and airsoft eye injuries, the severity profile that drives the airsoft surcharge.
- Specialty Insurance, "Airsoft vs Paintball Insurance" (internal): the sport-versus-sport premium comparison and the surcharge drivers behind airsoft pricing.
- Specialty Insurance, "The Action-Sports Coverage Gaps a Generalist Agent Will Miss" (internal): why a generalist General Liability policy leaves airsoft participants uninsured.
- Specialty Insurance, "Why Your Paintball Field's GL Policy Probably Has Gaps" (internal): how action-sports property and rental fleets get under-scheduled.